Sell a house when you owe more than it's worth in Florin
No repairs, no commissions, no waiting. A fair cash offer and a closing date you choose.

Licensed, verified, and reviewed by Sacramento sellers.
Every credential below links to the proof: the license, the filings, the certifications. The reviews are from real sellers on Google.
4.832 Google reviewsRead the Google reviews
On this page · 10 sections
- 01What being underwater really means for a Florin homeowner
- 02Why Florin tract homes can end up worth less than the loan
- 03Your real options when you owe more than the house is worth
- 04How a short sale actually works with your lender
- 05Why a direct cash buyer can be a steadier short sale alternative in Florin
- 06When you might not be as underwater as you think
- 07What to watch out for with national buyers and middlemen
- 08Why working with a local licensed broker matters here
- 09How fast you can actually move in Florin
- 10Talking with Darren about your Florin house
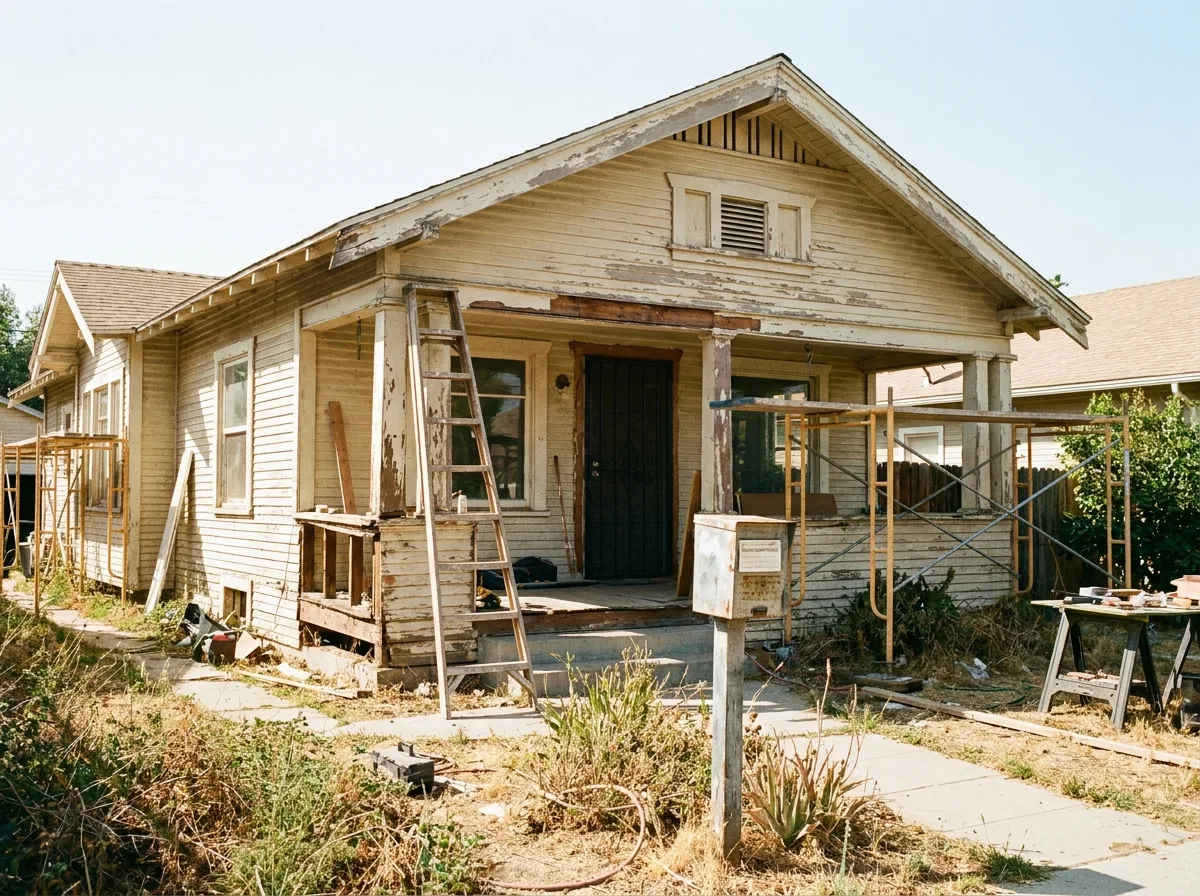
If you need to sell a house when you owe more than it's worth in Florin, you do not have to list it, fix it, or wait months for a buyer. Darren B. Brown buys it as-is for cash, with no repairs, no agent commissions, and no fees. Homes around Florin tend to sell below the regional median, and Darren will give you a fair, no-obligation number either way.
- Sacramento-area median sale price (mid-2026)
- $585,000
- Typical time on market for a listed home
- 33 days
- Darren can close in as few as
- 10 days
When you are underwater
If the loan balance exceeds the value, a short sale needs lender approval, which takes time and paperwork. Darren has worked these and can tell you honestly whether a sale pencils out.
How selling to Darren works
1. Tell Darren about the property
Call (916) 300-7962 or request an offer online. It takes a few minutes and there is no obligation.
2. Get your offer
Darren reviews the home and makes a fair, no-obligation cash offer, usually within 24 to 48 hours.
3. Close on your date
Pick the closing date that works for you. Darren covers standard closing costs and handles the rest, so you simply collect your proceeds.
What you skip when you sell direct
- No repairs, cleaning, or cleanouts
- No agent commissions or listing fees
- No showings or open houses
- No financing contingencies that fall through
- Close on the date you choose
About Florin
A diverse, affordable south-county area of postwar tract homes near the Florin Road corridor. Homes here (95823, 95828) are largely 1950s-1970s tract, and they tend to sell below the regional median. Darren buys across Florin in any condition.
What being underwater really means for a Florin homeowner
If you owe more on your Florin house than it would sell for, you still have options, but the path runs through your lender, not just a buyer. A sale that does not cover the loan balance is called a short sale, and it needs your lender's approval before anyone can close. That approval takes time and paperwork, and it is the single biggest factor in how this goes for you.
Florin is a place where this situation comes up more often than people expect. The neighborhoods around the Florin Road corridor, in the 95823 and 95828 zip codes, are largely 1950s through 1970s tract homes. They are affordable, diverse, and full of long-time owners, and homes here tend to sell below the Sacramento-area median sale price of $585,000 (mid-2026). If you refinanced at a high point, pulled cash out for a roof or a family need, or bought recently with little down, the math can turn against you even when the house itself is solid.
I have been buying houses directly from Sacramento-area owners since 1996, more than 30 years now, and the first thing I tell anyone in this spot is simple. Being underwater is not a moral failing and it is not the end of the road. It is a numbers problem, and numbers problems can be worked through honestly when someone lays them out plainly for you.
Why Florin tract homes can end up worth less than the loan
The short answer is that value in Florin is set by condition and by nearby sales, and both can work against an owner carrying a large balance. A postwar or 1960s tract house on a quiet street off Florin Road or near Franklin Boulevard is often priced by buyers against similar homes nearby. If those comparable homes sell below the regional median, your house is measured against that lower bar, no matter what you paid or borrowed.
Age matters too. Homes built in the 1950s through 1970s often carry original plumbing, older electrical panels, single-pane windows, tired roofs, and aging sewer lines. A retail buyer's inspector will find those things, and the buyer will ask for credits or walk away. Every dollar of repairs you would need to make before listing comes straight out of an equity cushion that, in your case, may already be gone.
That is why owners here sometimes feel stuck. They cannot afford to fix the house to get top dollar, and without the fixes, the house will not sell for enough to pay off the loan. Understanding that squeeze is the first step to choosing the right way out, whether that is a short sale, a direct cash sale, or simply staying put while you get advice.
Your real options when you owe more than the house is worth
You generally have four paths, and each one has trade-offs worth weighing before you sign anything. The first is to keep the house and keep paying, which can make sense if your income is steady and you simply want to wait for values to recover. The second is to list with an agent and pursue a short sale on the open market. The third is a direct sale to a cash buyer like me, either as a short sale or, if the numbers allow, as a regular sale. The fourth, which nobody wants, is letting the house go to foreclosure.
If you are also behind, the clock matters. I have written more about selling when you're behind on payments in Florin, and about selling before foreclosure in Florin if a notice has already arrived. California's nonjudicial foreclosure process is laid out in California Civil Code section 2924, and it is worth reading so you know where you stand.
Before you decide, I strongly suggest talking with a HUD-approved housing counselor. They are free or low cost, they do not work for a buyer, and they can tell you about loan modifications or programs you may qualify for. If keeping the house is realistic, I would rather you keep it. If it is not, you will walk into any sale with clearer eyes.
How a short sale actually works with your lender
A short sale is a sale where the lender agrees to accept less than the full payoff, and nothing closes until that lender signs off in writing. The buyer makes an offer, the offer goes to the lender along with a hardship package, and the lender reviews it. That package usually includes financial statements, bank records, pay information, and a letter explaining why you cannot keep the home.
The lender then orders its own valuation of the property and decides whether the offer is acceptable. They may counter, ask for more documents, or take longer than anyone would like. This is the part of the process where listed short sales tend to fall apart. A typical buyer on the open market, used to a listed home selling in about 33 days, often loses patience and walks away while the bank is still reviewing.
One question I hear constantly is whether the seller will owe money at closing. In an approved short sale, you typically do not bring cash to the table. I will confirm the specifics for your particular loan, because the terms the lender approves are what govern your outcome, and those details are worth reading carefully before you sign.
Why a direct cash buyer can be a steadier short sale alternative in Florin
A direct cash buyer removes the parts of a short sale most likely to collapse, which is why many owners look for a short sale alternative in Florin that does not depend on a retail buyer. When I make an offer, there is no mortgage underwriting on my side and no financing contingency that can fall through weeks into the lender's review. I am not going to vanish because a bank took longer than expected, because I know going in that it will.
I also buy as-is. That matters a great deal for a 1960s tract house with deferred maintenance. On a listed short sale, the lender sees a lower sale price if the buyer demands repair credits after inspection. With me, there are no repairs, no cleaning, and no showings, so the offer the lender reviews is the offer that actually closes. That predictability is something lenders tend to appreciate.
Sometimes the honest answer is that a short sale does not pencil out at all, or that you actually have a little more equity than you feared. I have worked these, and I will tell you straight either way. You can read more about how I approach alternatives to a short sale in Sacramento if you want the broader picture.
When you might not be as underwater as you think
Many Florin owners guess their value from a headline or an online estimate, and those guesses can be off in either direction. Before assuming the worst, gather your most recent mortgage statement with the payoff, any second loan or line of credit, and any unpaid property taxes. You can check your assessed details with the Sacramento County Assessor, though keep in mind that assessed value is not the same as market value.
If it turns out your home would sell for slightly more than you owe, you may be able to sell without lender approval at all. In that case, a direct sale where I cover standard closing costs and charge no agent commission can leave you with something in your pocket, or at least a clean break, where a traditional listing with commissions and repair credits might have pushed you into short sale territory.
That is one reason I always give a fair, no-obligation number. Knowing your real position is valuable even if you decide not to sell to me. Homes around Florin tend to sell below the regional median, and I factor that honestly into my number rather than inflating it to win your call.
What to watch out for with national buyers and middlemen
Be cautious of anyone who promises a short sale will close quickly or that you will definitely walk away with money, because no buyer can guarantee what your lender will approve. A lot of the postcards and ads you see in 95823 and 95828 come from national buyers or middlemen who lock up a contract and then try to resell it to someone else. If a short sale is involved, that extra layer can slow the lender review or kill the deal.
Here are a few questions worth asking any buyer before you sign:
Ask these, and listen closely to how they answer. A straight answer usually tells you everything about how the rest of the deal will go.
Are you the actual buyer, or will you assign this contract to someone else?
Are you licensed in California, and what is your license number?
Have you worked a short sale with a lender before, and what did you need from the seller?
Who pays closing costs, and will I be asked to bring any money?
Can I talk to a housing counselor or attorney before signing, without pressure?
Why working with a local licensed broker matters here
When your lender is going to scrutinize every number, it helps to work with someone accountable and local. I am a licensed California broker, DRE #01295232, and you can verify that yourself with the California DRE license lookup. I am also a retired Air Force veteran, and I run this the way I was trained: tell people the truth, do what you said, and finish the job.
Local knowledge matters in Florin specifically. I know the difference between the older streets closer to Florin Road and the slightly newer tracts farther out, and I know which kinds of age-related issues show up in homes from these decades. That helps me put together an offer a lender can understand and support, instead of a lowball number that gets rejected and costs you weeks.
I also buy in nearby areas where similar situations come up, so if you have family or a second property close by, I can help there too. I have written about alternatives to a short sale in South Sacramento and in Elk Grove, which share some of the same lender realities.
How fast you can actually move in Florin
If you need to sell your house fast in Florin, speed depends on whether a lender has to approve the sale. When there is enough equity to pay off the loan, I can close in as few as 10 days, and you pick the date that works for your move. Compared with the typical 33 days on market for a listed home, plus escrow time after that, the difference can mean a lot when money is tight.
With a short sale, the lender sets the pace. I cannot promise how long their review will take, and I will not pretend otherwise. What I can do is get you a fair offer, usually within 24 to 48 hours, help make sure the paperwork is complete, and be ready to close as soon as approval arrives. If you are also juggling a job change, a divorce, medical bills, or other strain, my page on selling during financial hardship in Florin may help.
While you wait, keep paying property taxes if you can, and check your balance with the Sacramento County Department of Finance. Unpaid taxes become one more lien that has to be sorted out at closing.
Talking with Darren about your Florin house
If you are looking for cash home buyers in Florin who will be honest about whether a sale makes sense, I would be glad to hear from you. We buy houses in Florin in any condition, from homes that need a full cleanout to ones that just need a new roof, and there is never any obligation to accept what I offer. You can learn more about selling a house fast in Florin or about selling your house fast in Sacramento generally.
The easiest way to start is a phone call to (916) 300-7962. Tell me what you owe, what shape the house is in, and what you are hoping for. I will tell you plainly whether a direct sale, a short sale, or holding on looks best, even if the best answer does not involve me buying your house.
After more than 30 years of doing this, I have learned that people in your position mostly want two things: a clear picture and someone they can trust to follow through. I can offer both, and I will treat your home and your situation with the respect they deserve.