Sell a house when you owe more than it's worth in Davis
No repairs, no commissions, no waiting. A fair cash offer and a closing date you choose.

Licensed, verified, and reviewed by Sacramento sellers.
Every credential below links to the proof: the license, the filings, the certifications. The reviews are from real sellers on Google.
4.832 Google reviewsRead the Google reviews
On this page · 9 sections
- 01What Being Underwater Really Means for a Davis Homeowner
- 02Why Davis Values Can Surprise Owners Who Think They Are Short
- 03How a Short Sale Actually Works When You Owe Too Much
- 04When a Cash Sale Is the Better Short Sale Alternative in Davis
- 05The Condition Problem in Older Davis Homes
- 06If Payments Are Already Slipping, Watch the Clock
- 07Questions to Ask Before You Choose a Path
- 08Why Working Locally Matters More Than a National Buyer
- 09What a Fair Conversation With Darren Looks Like
When you own a house when you owe more than it's worth in Davis, a direct sale is often the fastest way out. Darren B. Brown buys it as-is for cash, with no repairs, no agent commissions, and no fees. Homes around Davis tend to sell above the regional median, and Darren will give you a fair, no-obligation number either way.
- Sacramento-area median sale price (mid-2026)
- $585,000
- Typical time on market for a listed home
- 33 days
- Darren can close in as few as
- 10 days
When you are underwater
If the loan balance exceeds the value, a short sale needs lender approval, which takes time and paperwork. Darren has worked these and can tell you honestly whether a sale pencils out.
How selling to Darren works
1. Tell Darren about the property
Call (916) 300-7962 or request an offer online. It takes a few minutes and there is no obligation.
2. Get your offer
Darren reviews the home and makes a fair, no-obligation cash offer, usually within 24 to 48 hours.
3. Close on your date
Pick the closing date that works for you. Darren covers standard closing costs and handles the rest, so you simply collect your proceeds.
What you skip when you sell direct
- No repairs, cleaning, or cleanouts
- No agent commissions or listing fees
- No showings or open houses
- No financing contingencies that fall through
- Close on the date you choose
About Davis
A bike-friendly university city built around UC Davis, with tight inventory, strong rental demand, and many 1960s-90s homes. Homes here (95616, 95618) are largely 1960s-1990s + infill, and they tend to sell above the regional median. Darren buys across Davis in any condition.
What Being Underwater Really Means for a Davis Homeowner
If you owe more on your Davis house than it would sell for, you are not out of options, but you do need to understand which path actually works for your numbers before you sign anything. Being underwater simply means the loan balance is larger than the market value. On paper that sounds like a dead end. In practice it is a puzzle with a few possible solutions, and the right one depends on how far apart those two numbers are, how many loans sit on the property, and how much time you have.
Davis is an unusual place to be in this spot. Homes in 95616 and 95618 tend to sell above the Sacramento-area median of $585,000, inventory is tight, and rental demand stays strong because of UC Davis. That means many owners who feel underwater are closer to break-even than they think. Others, especially those who refinanced, took a second loan, or bought at a peak, really are short. Either way, the first job is getting an honest read on value.
I have bought houses directly from Sacramento-area owners since 1996, and I am a licensed California broker and a retired Air Force veteran. When someone calls me about an underwater house, I do not start by pitching a cash offer. I start by asking what you owe, what you think it is worth, and what you need out of the sale. Sometimes a direct sale makes sense. Sometimes it does not, and I will tell you that plainly.
Why Davis Values Can Surprise Owners Who Think They Are Short
The quickest way to find out whether you are truly underwater in Davis is to compare your payoff statement against what similar homes on your side of town are actually doing, not what an online estimate says. Davis housing is mostly 1960s through 1990s construction with newer infill mixed in, and those eras behave very differently on the market. A tidy 1970s ranch near a greenbelt and bike path can draw strong interest, while a dated 1980s two-story that needs a roof, windows, and an HVAC system may sit well below what its owner expects.
Because buyers here often include parents of students, investors looking for rentals, and university staff, demand stays steady even when the wider region slows. That support is a real advantage for an owner who is close to the line. It can be the difference between a short sale that needs lender approval and a regular sale where you walk away clean.
You can check your property's assessed details through the Yolo County Assessor, though keep in mind that assessed value under California rules is not the same as market value. For a real number, you need someone who looks at condition, location, and what buyers will pay right now. That is exactly the conversation I am happy to have, with no obligation either way.
How a Short Sale Actually Works When You Owe Too Much
A short sale is a sale where your lender agrees to accept less than the full loan balance so the house can sell. The key word is agrees. Nothing happens until the lender signs off, and that approval takes time and paperwork. You will typically be asked for financial statements, a hardship explanation, bank records, and tax documents, and the lender will order its own valuation of the house.
The upside is real. In an approved short sale you typically do not bring cash to closing, and you avoid the heavier damage of a foreclosure. The downside is the uncertainty. A listed home in this region typically sits about 33 days on market before you even get to the lender review, and lenders can counter, ask for more documents, or change their minds. If there is a second loan or a home equity line, both lenders usually need to agree, which adds another layer.
I have worked these files, and the most helpful thing I can offer is honesty about whether a deal pencils out before you spend months on it. If you want a broader look at how these deals play out across the region, my page on alternatives to a short sale in Sacramento walks through the bigger picture. In Davis, the strong price support often gives sellers more room to negotiate than they expect.
When a Cash Sale Is the Better Short Sale Alternative in Davis
If you are only slightly underwater, or close to even once you factor in what a traditional sale would cost you, a direct cash sale can be the simplest short sale alternative in Davis. A listed sale usually carries agent commissions, repair requests after inspection, staging, and showings. Those costs can push a break-even house into short territory. When I buy directly, there are no commissions and no fees, I buy as-is, and I cover standard closing costs. That can close the gap.
Speed matters too. I can close in as few as 10 days when the numbers work, compared with a typical 33 days on market for a listed home before escrow even begins. For an owner facing rising late fees or a lender deadline, those weeks are not trivial. If you need to sell your house fast in Davis, a clean, predictable closing date can be worth as much as a slightly higher listing price that may never materialize.
There is a limit, and I want to be straight about it. If the loan balance is far above what any buyer would pay, a cash sale cannot make that difference disappear without the lender agreeing to take less. In that case we are back to lender approval, and I can help you think it through. Cash home buyers in Davis who promise otherwise are telling you what you want to hear.
The Condition Problem in Older Davis Homes
For many underwater owners in Davis, the real obstacle is not the loan, it is the house. Homes built in the 1960s, 70s, and 80s often come with original plumbing, aging roofs, older electrical panels, single-pane windows, and foundations that have shifted over decades of Yolo County clay soil and dry summers. A buyer using a mortgage will order an inspection, and a lender's appraiser will flag issues. Each one can become a repair demand or a price cut.
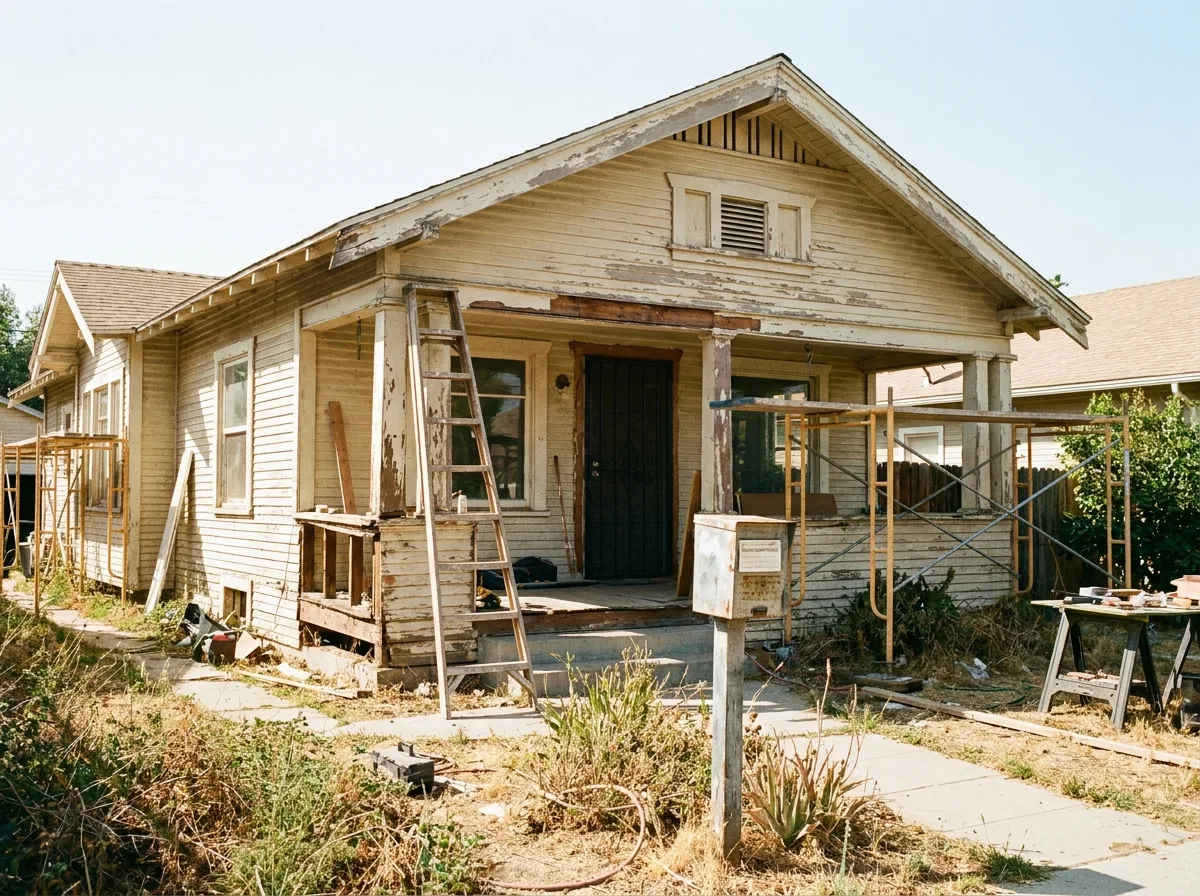
When you are already short on equity, you probably do not have spare cash for a new roof or a sewer line replacement. That is a trap: you cannot sell without repairs, and you cannot afford repairs because you cannot sell. Former rentals near campus have an extra layer of wear, from worn flooring to tired kitchens, that a retail buyer will notice right away.
I buy across Davis in any condition, which removes that trap entirely. You do not fix, clean, or clear out the house first. If you want to learn more about how I approach any home here, see my page on how we buy houses in Davis. The point is simple: the condition of the house should not be what keeps you stuck.
If Payments Are Already Slipping, Watch the Clock
The most important thing an underwater owner who has missed payments can do is act early, because the formal foreclosure process in California follows set steps and your options shrink as it moves forward. The rules for notices and timing under a deed of trust are laid out in California Civil Code section 2924. I am not your attorney, and you should get legal advice on your specific situation, but reading that section will help you understand why waiting is costly.
A short sale started late may run out of time before the lender finishes its review. A direct sale started early leaves room to pick the path that fits. If you are a month or two behind, my guide to selling when you're behind on payments in Davis covers that stage. If notices have already arrived, read about selling before foreclosure in Davis so you know what is realistic.
It is also worth talking with a HUD-approved housing counselor. They are free or low cost and can explain loan modification and forbearance options. Sometimes keeping the house is possible, and if it is, I would rather you know that before you sell.
Questions to Ask Before You Choose a Path
Before deciding between a short sale, a listing, or a direct sale, gather a few facts so you can compare options honestly. These are the questions I walk through with Davis owners, and they are worth answering whether or not you ever call me.
Once you have these answers, the right path often becomes obvious. If the gap is small, a direct sale may cover it. If it is large, lender approval is unavoidable, and the question becomes how to get there with the least stress.
What is the exact payoff on every loan, including any second mortgage or equity line?
Are there property tax, HOA, or lien balances that would also need to be paid?
What would the house need before a retail buyer's inspector signed off?
How many months can you realistically keep paying, if at all?
Is a tenant or student renter living there, and what is their lease status?
Do you need a specific move-out date for a job, school, or family reason?
Why Working Locally Matters More Than a National Buyer
When your house is underwater, the buyer you work with matters, because short sale files and tight-margin deals fall apart easily when the other side does not know the area or the process. Many national buyers and middlemen put a house under contract, then shop it to someone else or renegotiate after an inspection. For an owner with no equity cushion, a lowered price late in the deal can turn a workable sale into a short one.
I am one person, and I have bought in this region for more than 30 years. I know the difference between North Davis, the older neighborhoods near downtown, and the newer infill on the edges of town, and I price with that in mind. You can verify my license, DRE #01295232, through the California DRE license lookup before you share a single document.
I also work the neighboring Yolo County and river communities. If you own elsewhere too, see my pages on alternatives to a short sale in Woodland and in West Sacramento. Same honest approach, adjusted for each market.
What a Fair Conversation With Darren Looks Like
The first call is a conversation, not a commitment. You tell me about the house and what you owe, and I give you my honest read on whether a direct sale, a short sale, or another path makes the most sense. If a cash offer fits, I typically have a number for you within 24 to 48 hours, and you pick the closing date. If it does not fit, I will say so and point you toward what might.
Underwater situations often come with other pressure: a job change, a divorce, medical bills, or a lost renter. If money is tight in more ways than the mortgage, my page on selling during financial hardship in Davis may help. You deserve a clear picture without a sales pitch attached.
When you are ready, call me at (916) 300-7962. We will look at your numbers together, plainly and respectfully, and figure out the way forward that leaves you in the best possible position.