Sell a house when you owe more than it's worth in Woodland
No repairs, no commissions, no waiting. A fair cash offer and a closing date you choose.

Licensed, verified, and reviewed by Sacramento sellers.
Every credential below links to the proof: the license, the filings, the certifications. The reviews are from real sellers on Google.
4.832 Google reviewsRead the Google reviews
On this page · 10 sections
- 01What being underwater on a Woodland house really means for you
- 02Why Woodland homes feel the squeeze differently than Sacramento
- 03The older bungalow problem near Main Street
- 04Spring Lake and the newer subdivisions: a different kind of underwater
- 05Your real options when you owe more than the house is worth
- 06How a direct cash sale fits into a Woodland short sale
- 07When the timing turns urgent: missed payments and foreclosure notices
- 08What to watch out for with cash home buyers in Woodland
- 09Getting your numbers straight before you decide
- 10Selling your Woodland house fast without making things worse
A house when you owe more than it's worth in Woodland can be hard to sell the traditional way. There is a simpler path. Darren B. Brown buys it as-is for cash, with no repairs, no agent commissions, and no fees. Homes around Woodland tend to sell below the regional median, and Darren will give you a fair, no-obligation number either way.
- Sacramento-area median sale price (mid-2026)
- $585,000
- Typical time on market for a listed home
- 33 days
- Darren can close in as few as
- 10 days
When you are underwater
If the loan balance exceeds the value, a short sale needs lender approval, which takes time and paperwork. Darren has worked these and can tell you honestly whether a sale pencils out.
How selling to Darren works
1. Tell Darren about the property
Call (916) 300-7962 or request an offer online. It takes a few minutes and there is no obligation.
2. Get your offer
Darren reviews the home and makes a fair, no-obligation cash offer, usually within 24 to 48 hours.
3. Close on your date
Pick the closing date that works for you. Darren covers standard closing costs and handles the rest, so you simply collect your proceeds.
What you skip when you sell direct
- No repairs, cleaning, or cleanouts
- No agent commissions or listing fees
- No showings or open houses
- No financing contingencies that fall through
- Close on the date you choose
About Woodland
The Yolo County seat, an agricultural town with a historic downtown, older bungalows near Main Street, and newer Spring Lake subdivisions. Homes here (95695, 95776) are largely 1920s-1960s core + 2000s growth, and they tend to sell below the regional median. Darren buys across Woodland in any condition.
What being underwater on a Woodland house really means for you
If you owe more on your Woodland home than it would sell for, you are not out of options, but the usual way of selling probably will not work without your lender's cooperation. When the loan balance is higher than the value, a traditional sale cannot pay off the mortgage, so the bank has to agree to accept less. That agreement is called a short sale, and it takes time and paperwork.
This situation is more common than most people admit to their neighbors. Homes around Woodland tend to sell below the Sacramento-area median, which was $585,000 in mid-2026. If you bought or refinanced at a peak, took out a second loan, or added a home equity line for repairs or family needs, the math can tip upside down without you doing anything wrong. Many people in your spot feel embarrassed or stuck. You do not need to be either. You need a clear picture of what the house is worth, what you owe, and which path costs you the least.
I am Darren B. Brown. I have bought houses directly from Sacramento-area owners since 1996, and I have worked through underwater situations before. My job on the first call is not to sell you on anything. It is to tell you honestly whether a sale pencils out, and if it does not, to say so.
Why Woodland homes feel the squeeze differently than Sacramento
Woodland is its own market, and that matters when you are underwater. As the Yolo County seat and an agricultural town, it has a steady, practical character, but values here tend to run below the regional median. A buyer comparing Woodland to Natomas or Elk Grove sees lower prices, and appraisals follow the local sales, not the Sacramento headline number. That gap is often exactly why an owner ends up owing more than a buyer will pay.
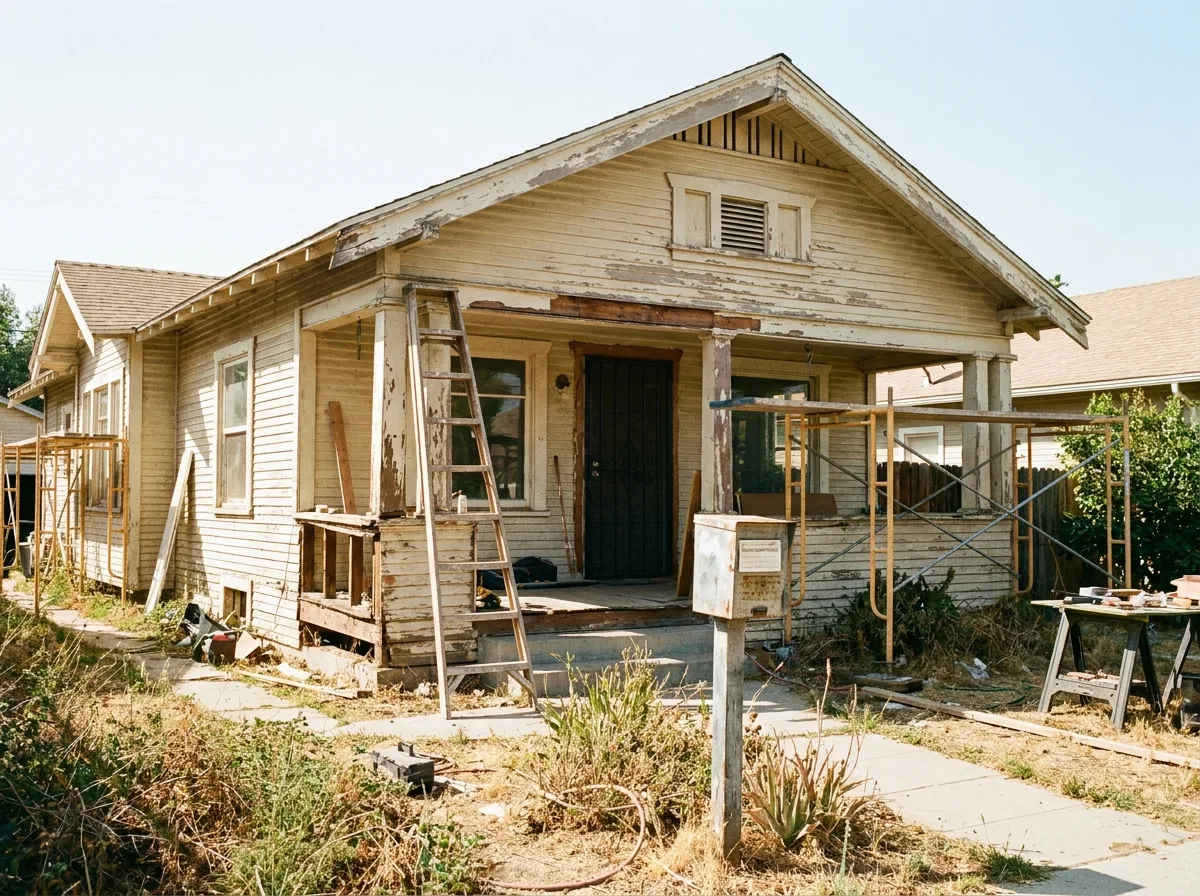
The housing stock also splits in two. Near Main Street and the historic downtown you find older bungalows and homes from the 1920s through the 1960s, many with original wiring, aging plumbing, or foundations that have settled over the decades. Out toward Spring Lake, the 2000s subdivisions are newer, but many of those homes were bought or refinanced at prices that local sales have not always supported since. Each group lands underwater for different reasons, and each needs a different conversation.
If you want a broader look at how I buy in town regardless of equity, you can read about how we buy houses in Woodland, across both 95695 and 95776.
The older bungalow problem near Main Street
For an underwater owner in one of Woodland's older core neighborhoods, repairs are often the hidden reason a listing will not close. A 1940s or 1950s bungalow can be charming and still have issues that only surface during a buyer's inspection. When that happens on a normal listing, the buyer asks for credits or walks away. When you are already short on equity, you have no room to give those credits, and the deal falls apart.
Lenders reviewing a short sale look at the offer price and the property condition together. A house that needs a roof, an electrical update, or sewer line work will draw lower offers from retail buyers, and some buyers using standard loans cannot finance a home in rough shape at all. That can stretch a short sale out for months while you keep living with the uncertainty.
Because I buy as-is for cash, the condition of an older home near downtown is something I factor in up front rather than discover late. You do not need to fix, clean, or clear anything out. That does not make an underwater balance disappear, but it removes the inspection surprises that so often derail Woodland short sales on older homes.
Spring Lake and the newer subdivisions: a different kind of underwater
In the Spring Lake area and other 2000s growth neighborhoods, the house itself is usually in decent shape, and the problem is mostly the loan. Owners there may have bought near a high point, taken cash out during a refinance, or layered a second mortgage on top. The home shows well, yet the combined balance still exceeds what comparable Woodland sales support.
For these owners, the question is less about condition and more about whether the lender or lenders will approve a payoff below what is owed. If there are two loans, both have to sign off, and the second lienholder often wants something to release its claim. That can add weeks of back and forth. A newer home in good condition may also be competing with similar listings nearby, so price matters.
When you call me, I will ask about every loan on the property, not just the first mortgage. That is the honest starting point. Sometimes the numbers are closer than an owner fears. Sometimes they are not, and I would rather you know that early than spend months hoping.
Your real options when you owe more than the house is worth
You generally have a handful of realistic paths, and the right one depends on your timeline, your loan, and how much stress you can carry. None is perfect, so it helps to see them side by side before you decide anything.
Before choosing, it is worth talking with a neutral party. A HUD-approved housing counselor can review loan modification or hardship programs at no cost, and that conversation may change your plan. I encourage it.
Keep the home and ask your lender about a modification or repayment plan, if you can afford the payment going forward.
List with an agent as a short sale, which needs lender approval and usually takes longer than a typical listing.
Sell directly for cash as a short sale alternative in Woodland, where the lender still must approve any payoff below the balance, but the buyer side is simple and certain.
Bring cash to closing to cover the shortfall, if you have savings and want a clean exit.
Wait, if values or your balance are close enough that time might close the gap.
How a direct cash sale fits into a Woodland short sale
A cash sale does not replace the lender's approval when you are underwater, but it can make that approval easier to get and faster to finish. Lenders reviewing short sales worry about buyers whose financing collapses or who demand repairs midway through. A cash buyer with no financing contingency removes much of that risk, and that gives the bank a cleaner file to approve.
Here is how it plays out. I review the home and make a fair, no-obligation offer, usually within 24 to 48 hours. If the offer is below what you owe, that offer becomes part of the short sale package your lender reviews. Once approved, I can close in as few as 10 days, compared with a typical 33 days on market for a listed home, plus escrow, before the short sale clock even starts.
In an approved short sale, you typically do not bring cash to closing. I will confirm the specifics for your loan, because every lender writes its approval a little differently. For a wider look at the approach, see my page on alternatives to a short sale in Sacramento.
When the timing turns urgent: missed payments and foreclosure notices
If you have already missed payments, the calendar matters as much as the math. Underwater owners often fall behind because the payment no longer feels worth it, or because a job, illness, or family change hit at the same time. Once payments lapse, the lender can begin the foreclosure process, and California lays out those steps in California Civil Code section 2924.
A short sale is often still possible after a notice arrives, but you have less room to wait. Lenders sometimes move both tracks at once, so starting the conversation early protects your options. I am not a lawyer and will not give legal advice, but I can tell you quickly whether a direct sale is worth pursuing alongside whatever your lender or counselor suggests.
If you are earlier in the process, my page on selling when you're behind on payments in Woodland goes deeper. If a notice is already on your door, read about selling before foreclosure in Woodland and call me sooner rather than later.
What to watch out for with cash home buyers in Woodland
Not every cash home buyer in Woodland treats underwater owners well, so ask hard questions before you sign anything. Some national buyers and middlemen lock up a contract at one number and then lower it after an inspection, knowing you are short on time. Others sign you up and then assign the contract to someone else, which can stall a short sale when the lender asks who is actually buying.
Ask who will be on the title at closing. Ask whether the offer changes after a walkthrough. Ask whether they have worked through lender approval before, and whether they will be honest if the numbers do not work. A buyer who promises a short sale will definitely be approved is telling you something no one can promise.
You can verify my broker license, DRE #01295232, through the California DRE license lookup. I am a retired Air Force veteran and a local buyer, not a national middleman, and I would rather lose a deal than mislead you.
Getting your numbers straight before you decide
The best first step is to gather what you owe and get an honest sense of what the house is worth today. Pull your most recent mortgage statement and any second loan or line of credit statements. Note any unpaid property taxes, which you can check through the Yolo County Assessor and related county offices, along with any liens you know about.
Then compare that total with what similar Woodland homes have actually sold for, keeping in mind that local values tend to run below the regional median. If the gap is small, you may have more options than you think. If it is large, a short sale or a lender workout becomes the realistic conversation. When money is tight across the board, my page on selling during financial hardship in Woodland may help.
I cover standard closing costs, and there are no agent commissions or fees on my side. That matters on an underwater sale, because every dollar not lost to commissions is a dollar that can count toward the lender's payoff.
Selling your Woodland house fast without making things worse
If you want to sell your house fast in Woodland while underwater, speed only helps if it comes with honesty. Rushing into the wrong deal can leave you with a failed escrow and less time than before. The goal is a clear answer quickly, then a plan that fits your loan and your life.
I buy throughout Woodland in any condition, from downtown bungalows to Spring Lake homes, and across the greater Sacramento area. If you have family or a second property nearby, I also work short sale alternatives in Davis. You pick the closing date that works for you once the lender approves.
When you are ready, call me at (916) 300-7962. Tell me what you owe and what is going on. There is no obligation, and if a sale does not pencil out, I will tell you plainly and point you toward someone who can help.