Sell a house when you owe more than it's worth in North Highlands
No repairs, no commissions, no waiting. A fair cash offer and a closing date you choose.

Licensed, verified, and reviewed by Sacramento sellers.
Every credential below links to the proof: the license, the filings, the certifications. The reviews are from real sellers on Google.
4.832 Google reviewsRead the Google reviews
On this page · 10 sections
- 01What it means to owe more than your North Highlands house is worth
- 02Why North Highlands homes get caught in the gap
- 03How a short sale really works, and why it takes time
- 04When a direct cash sale can be a short sale alternative in North Highlands
- 05Condition issues common in 1950s and 1960s North Highlands houses
- 06If you are behind on payments or facing foreclosure
- 07Will you owe money at closing in an underwater sale?
- 08Cash home buyers in North Highlands: what to watch out for
- 09Gathering the right information before you decide
- 10How to sell your house fast in North Highlands without making it worse
If you need to sell a house when you owe more than it's worth in North Highlands, you do not have to list it, fix it, or wait months for a buyer. Darren B. Brown buys it as-is for cash, with no repairs, no agent commissions, and no fees. Homes around North Highlands tend to sell below the regional median, and Darren will give you a fair, no-obligation number either way.
- Sacramento-area median sale price (mid-2026)
- $585,000
- Typical time on market for a listed home
- 33 days
- Darren can close in as few as
- 10 days
When you are underwater
If the loan balance exceeds the value, a short sale needs lender approval, which takes time and paperwork. Darren has worked these and can tell you honestly whether a sale pencils out.
How selling to Darren works
1. Tell Darren about the property
Call (916) 300-7962 or request an offer online. It takes a few minutes and there is no obligation.
2. Get your offer
Darren reviews the home and makes a fair, no-obligation cash offer, usually within 24 to 48 hours.
3. Close on your date
Pick the closing date that works for you. Darren covers standard closing costs and handles the rest, so you simply collect your proceeds.
What you skip when you sell direct
- No repairs, cleaning, or cleanouts
- No agent commissions or listing fees
- No showings or open houses
- No financing contingencies that fall through
- Close on the date you choose
About North Highlands
A postwar community near the former McClellan airfield, with affordable single-story homes. Homes here (95660) are largely 1950s-1960s, and they tend to sell below the regional median. Darren buys across North Highlands in any condition.
What it means to owe more than your North Highlands house is worth
If you owe more on your North Highlands home than it would sell for, you have a few real paths: keep paying and wait, ask your lender to approve a short sale, or find out whether a direct cash sale can cover what you owe. The right answer depends on your loan balance, your home's condition, and how much time you have. Nobody should push you into one of those before you know the numbers.
Being underwater is not a moral failing, and it is more common than people admit. Plenty of owners in 95660 bought or refinanced at a high point, pulled cash out for a car or a medical bill, or took a second loan for a roof. Then values settled, and the gap between the payoff and the price stopped being a theory and became a problem.
Darren B. Brown has bought houses directly from Sacramento-area owners since 1996, more than 30 years. In that time he has sat at a lot of kitchen tables with people in exactly this spot. What he offers first is an honest read on whether a sale pencils out. Sometimes it does. Sometimes the better move is a short sale, a loan modification, or simply holding on, and he will tell you that plainly.
Why North Highlands homes get caught in the gap
Homes in North Highlands tend to sell below the regional median, and that one fact shapes everything about an underwater sale here. The Sacramento-area median sale price was $585,000 in mid-2026, but a modest single-story house off Watt Avenue or Elkhorn Boulevard usually trades for less than that. When your loan was written against a hopeful appraisal, the lower local ceiling can leave you short.
This is a postwar community that grew up around the former McClellan airfield. Most of the housing stock in 95660 went up in the 1950s and 1960s, built for airmen, civilian workers, and young families who needed an affordable first home. Those simple ranch houses on slab foundations were built quickly and well enough, but after sixty or seventy years they carry the wear you would expect.
That age matters when you owe a lot. A buyer using a conventional or FHA loan will often face an appraiser and an inspector who flag original electrical panels, galvanized plumbing, aging roofs, and single-pane windows. Each flagged item can push a listed price lower or kill a deal outright, which widens the very gap you are trying to close. Understanding that dynamic is the first step in choosing a path that actually works for your house.
How a short sale really works, and why it takes time
A short sale is a sale where your lender agrees to accept less than the full loan balance, and it only happens with the lender's approval. That approval is the whole ballgame. You can have a willing buyer and a signed contract, but until the bank signs off, nothing closes.
Getting that sign-off takes time and paperwork. Lenders typically want to see why you cannot keep paying, what you earn, what you spend, and what the house is honestly worth. They may order their own valuation. If there is a second loan or a home equity line, that lender has to agree too, and the two do not always see eye to eye. Each round of questions can add weeks.
Here is the trade-off many owners do not hear up front: a listed home in the region typically sits on the market for 33 days before a buyer even appears, and a short sale adds the lender review on top of that. Darren has worked these, so he can look at your situation and tell you whether it is realistic or whether you would be spending months chasing an approval that is unlikely. You can read more about alternatives to a short sale in Sacramento if you want the broader picture.
When a direct cash sale can be a short sale alternative in North Highlands
A direct cash sale works as a short sale alternative in North Highlands when the offer is close enough to your payoff that you, or a small negotiated concession, can bridge the difference. In that case you skip the long listing period and the uncertainty of a buyer's financing. Darren buys as-is, with no repairs, no agent commissions, and no fees, so more of the sale price goes toward your loan instead of to costs.
That last point is easy to overlook. On a traditional listing, commissions and seller-paid costs come straight out of your proceeds. When you are already underwater, those dollars can be the difference between a sale that works and one that does not. Removing them can change the math on a house that looked hopeless on paper.
If the numbers still fall short, a cash buyer can sometimes be the buyer in a short sale itself. Because Darren is not relying on a mortgage approval, the lender is looking at an offer that will not fall apart over an appraisal or a loan denial. That certainty can make a bank more comfortable approving. Either way, you get a fair, no-obligation number first, and you decide.
Condition issues common in 1950s and 1960s North Highlands houses
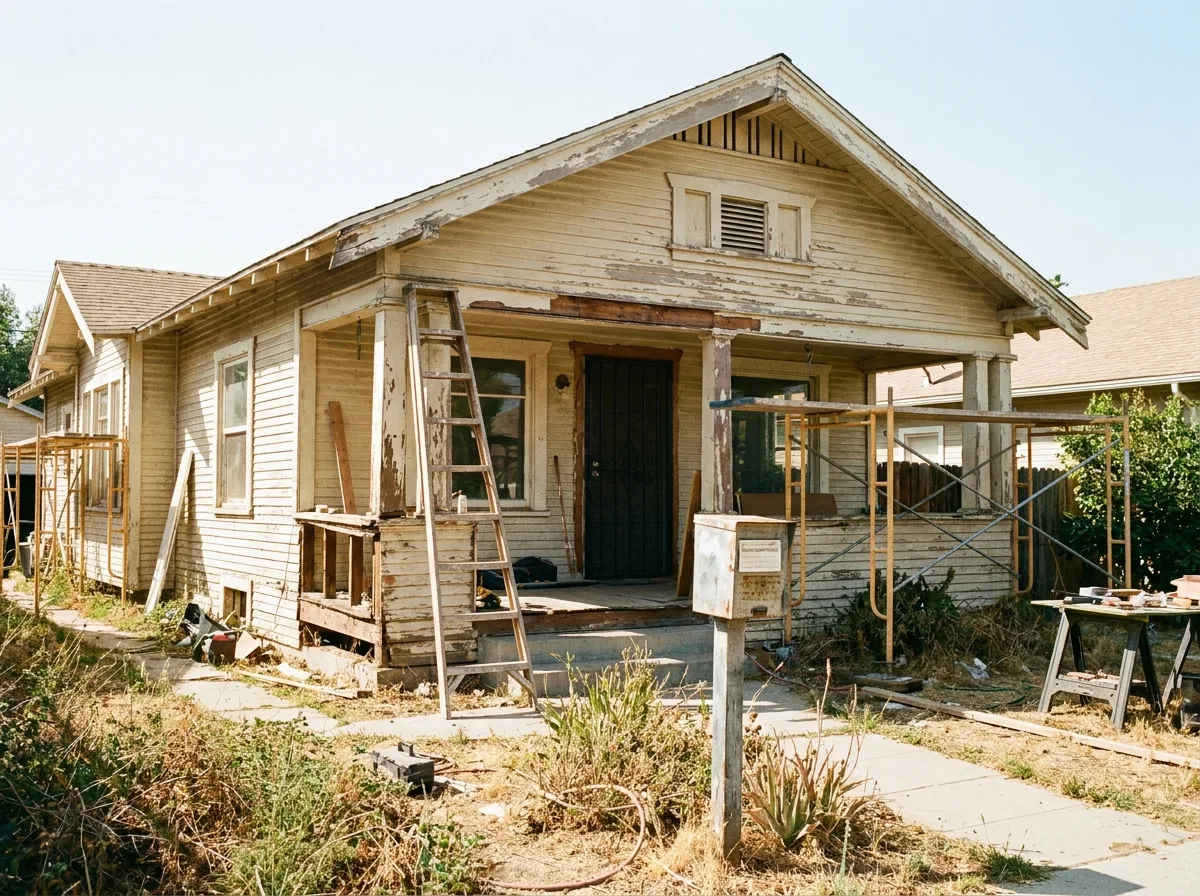
The older homes in North Highlands often have repair needs that make a traditional sale harder, and when you owe more than the house is worth, you usually do not have spare cash to fix them. That is exactly the bind a lot of local owners land in. The house needs work to sell for top dollar, but putting money in only digs the hole deeper.
Typical issues in this era of housing include original or undersized electrical service, older plumbing, tired HVAC systems, foundation cracks in slab homes, and roofs past their life. Some houses had additions or garage conversions done years ago without permits. Yards may have overgrown trees near the sewer line. None of that is unusual for a neighborhood built for McClellan families in the postwar boom.
Darren buys across North Highlands in any condition, so none of it has to be fixed, cleaned, or hidden. You are not trying to win over a picky retail buyer or a lender's appraiser. If you want to see how he approaches homes throughout the area, his page on how we buy houses in North Highlands covers it.
If you are behind on payments or facing foreclosure
If you are already missing payments, time becomes the most important factor, and you should act before the foreclosure process gets far along. In California, the foreclosure process for most home loans is governed by statute, including California Civil Code section 2924, which sets out notice requirements. Reading it will not solve your problem, but it helps to know there is a defined process with steps.
The earlier you talk to someone, the more options you have. A short sale started late can run out of runway. A cash sale, by contrast, can close in as few as 10 days when the numbers work and the lender cooperates, which can matter a great deal when a sale date is approaching. Darren will be candid about whether the timeline is realistic for your file.
There are pages specifically for selling when you are behind on payments and for selling before foreclosure in North Highlands if either describes where you are. It is also worth speaking with a free HUD-approved housing counselor, who can explain modification and forbearance options that do not involve selling at all.
Will you owe money at closing in an underwater sale?
In an approved short sale, you typically do not bring cash to closing. The lender agrees to take what the sale produces, and the closing is structured around that. That said, every loan is different, and Darren will confirm the specifics for your loan rather than promise something he cannot see yet.
With a direct cash sale that covers your payoff, the question looks different. Darren covers standard closing costs, which means you are not paying for them out of the proceeds. If the offer is short of your balance, that is the moment to talk honestly about whether a short sale, a small contribution from you, or waiting makes more sense.
The point is to know before you sign anything. A good buyer walks you through the payoff, the offer, and what is left over or missing, in plain language. If anyone tells you a sale will be free and clear without looking at your loan statement, be cautious.
Cash home buyers in North Highlands: what to watch out for
Not every cash buyer is the same, and in an underwater situation the difference matters. Some cash home buyers in North Highlands are local investors who will actually close. Others are middlemen who sign you to a contract, then try to resell that contract to a national buyer at a higher price. If they cannot, the deal quietly dies weeks later, and you have lost time you did not have.
A few questions help sort them out. Who is actually buying the house? Are they licensed? Have they handled a short sale before? Will they show you how they arrived at the number? Darren is a licensed California broker, DRE #01295232, and you can verify that yourself through the California DRE license lookup.
He is also a retired Air Force veteran, which carries some meaning in a community built around an airfield. Plenty of North Highlands families have military roots, and he tends to approach a hard conversation the way he was trained to: straightforward, no games, and focused on the mission, which here is getting you out of a bad spot as cleanly as possible.
Gathering the right information before you decide
The most useful thing you can do today is pull together a few documents so you can see your real position. With the facts in hand, the decision usually gets clearer and less frightening.
Having these ready lets Darren, a lender, or a housing counselor give you a real answer quickly instead of a guess:
Your most recent mortgage statement, plus statements for any second loan or home equity line
Any letters from your lender about missed payments or default
Your property tax status, which you can check with the Sacramento County Department of Finance
A short, honest list of known problems with the house, such as roof, plumbing, or foundation issues
Notes on your timeline, including any move, job change, or date you need to be out
How to sell your house fast in North Highlands without making it worse
The best way to sell your house fast in North Highlands when you are underwater is to start with an honest number and a clear timeline, not with repairs or a listing agreement. Calling (916) 300-7962 takes a few minutes, carries no obligation, and gets you a fair cash offer, usually within 24 to 48 hours. From there you can compare it to your payoff and see where you stand.
If the offer covers what you owe, you can pick a closing date that fits your life. If it does not, Darren will explain whether a short sale is worth pursuing, and whether he would be the buyer in it. If neither makes sense, he will say so. Homeowners in nearby areas face similar choices, and you can compare notes on short sale alternatives in Del Paso Heights or read about selling during financial hardship.
Owing more than your home is worth feels heavy, but it is a problem with a shape and a set of answers. Get the numbers, understand your options, and choose the one that leaves you in the best position for what comes next. Darren has been helping Sacramento-area owners do exactly that for more than 30 years.